A pay rise that takes someone over £100,000 can look great on paper, but the next payslip often tells a different story when take-home pay barely shifts, and the ‘extra’ money seems to vanish into tax and lost allowances.
Rakhee Wood says this happens when people treat a promotion, bonus, or salary jump as a simple win without checking how the UK tax system reacts once income crosses key thresholds.
Rakhee Wood is an Independent Financial Adviser at Butterfly Financial Planning in Kent, with over 20 years of experience helping individuals and families make clear, practical financial decisions during major life changes, including managing increased income and new opportunities.
Her work often focuses on reducing financial stress by mapping out how real choices – like taking a bonus, changing pension contributions, or claiming family support – affect both today’s tax bill and longer-term plans.
“Crossing the £100,000 income threshold is often seen as a major financial milestone, but what many people don’t realise is that it can trigger some of the most complicated tax rules in the UK system. Without the right structure in place, people can find themselves paying a higher effective tax rate than they anticipated, simply because their income has crossed into a different band.”
Not increasing pension contributions after a pay rise
One of the most common mistakes is keeping pension contributions exactly the same after moving above £100,000, even though the tax rules change significantly at this level.
Once adjusted net income crosses £100,000, the Personal Allowance starts to reduce, which can effectively increase your marginal tax rate. Increasing pension contributions can bring adjusted net income back down, which may help reduce the tax hit and, in some cases, preserve more of the allowance.
Ignoring this means people often end up paying more tax than they need to, simply because nothing was adjusted after the salary increase.
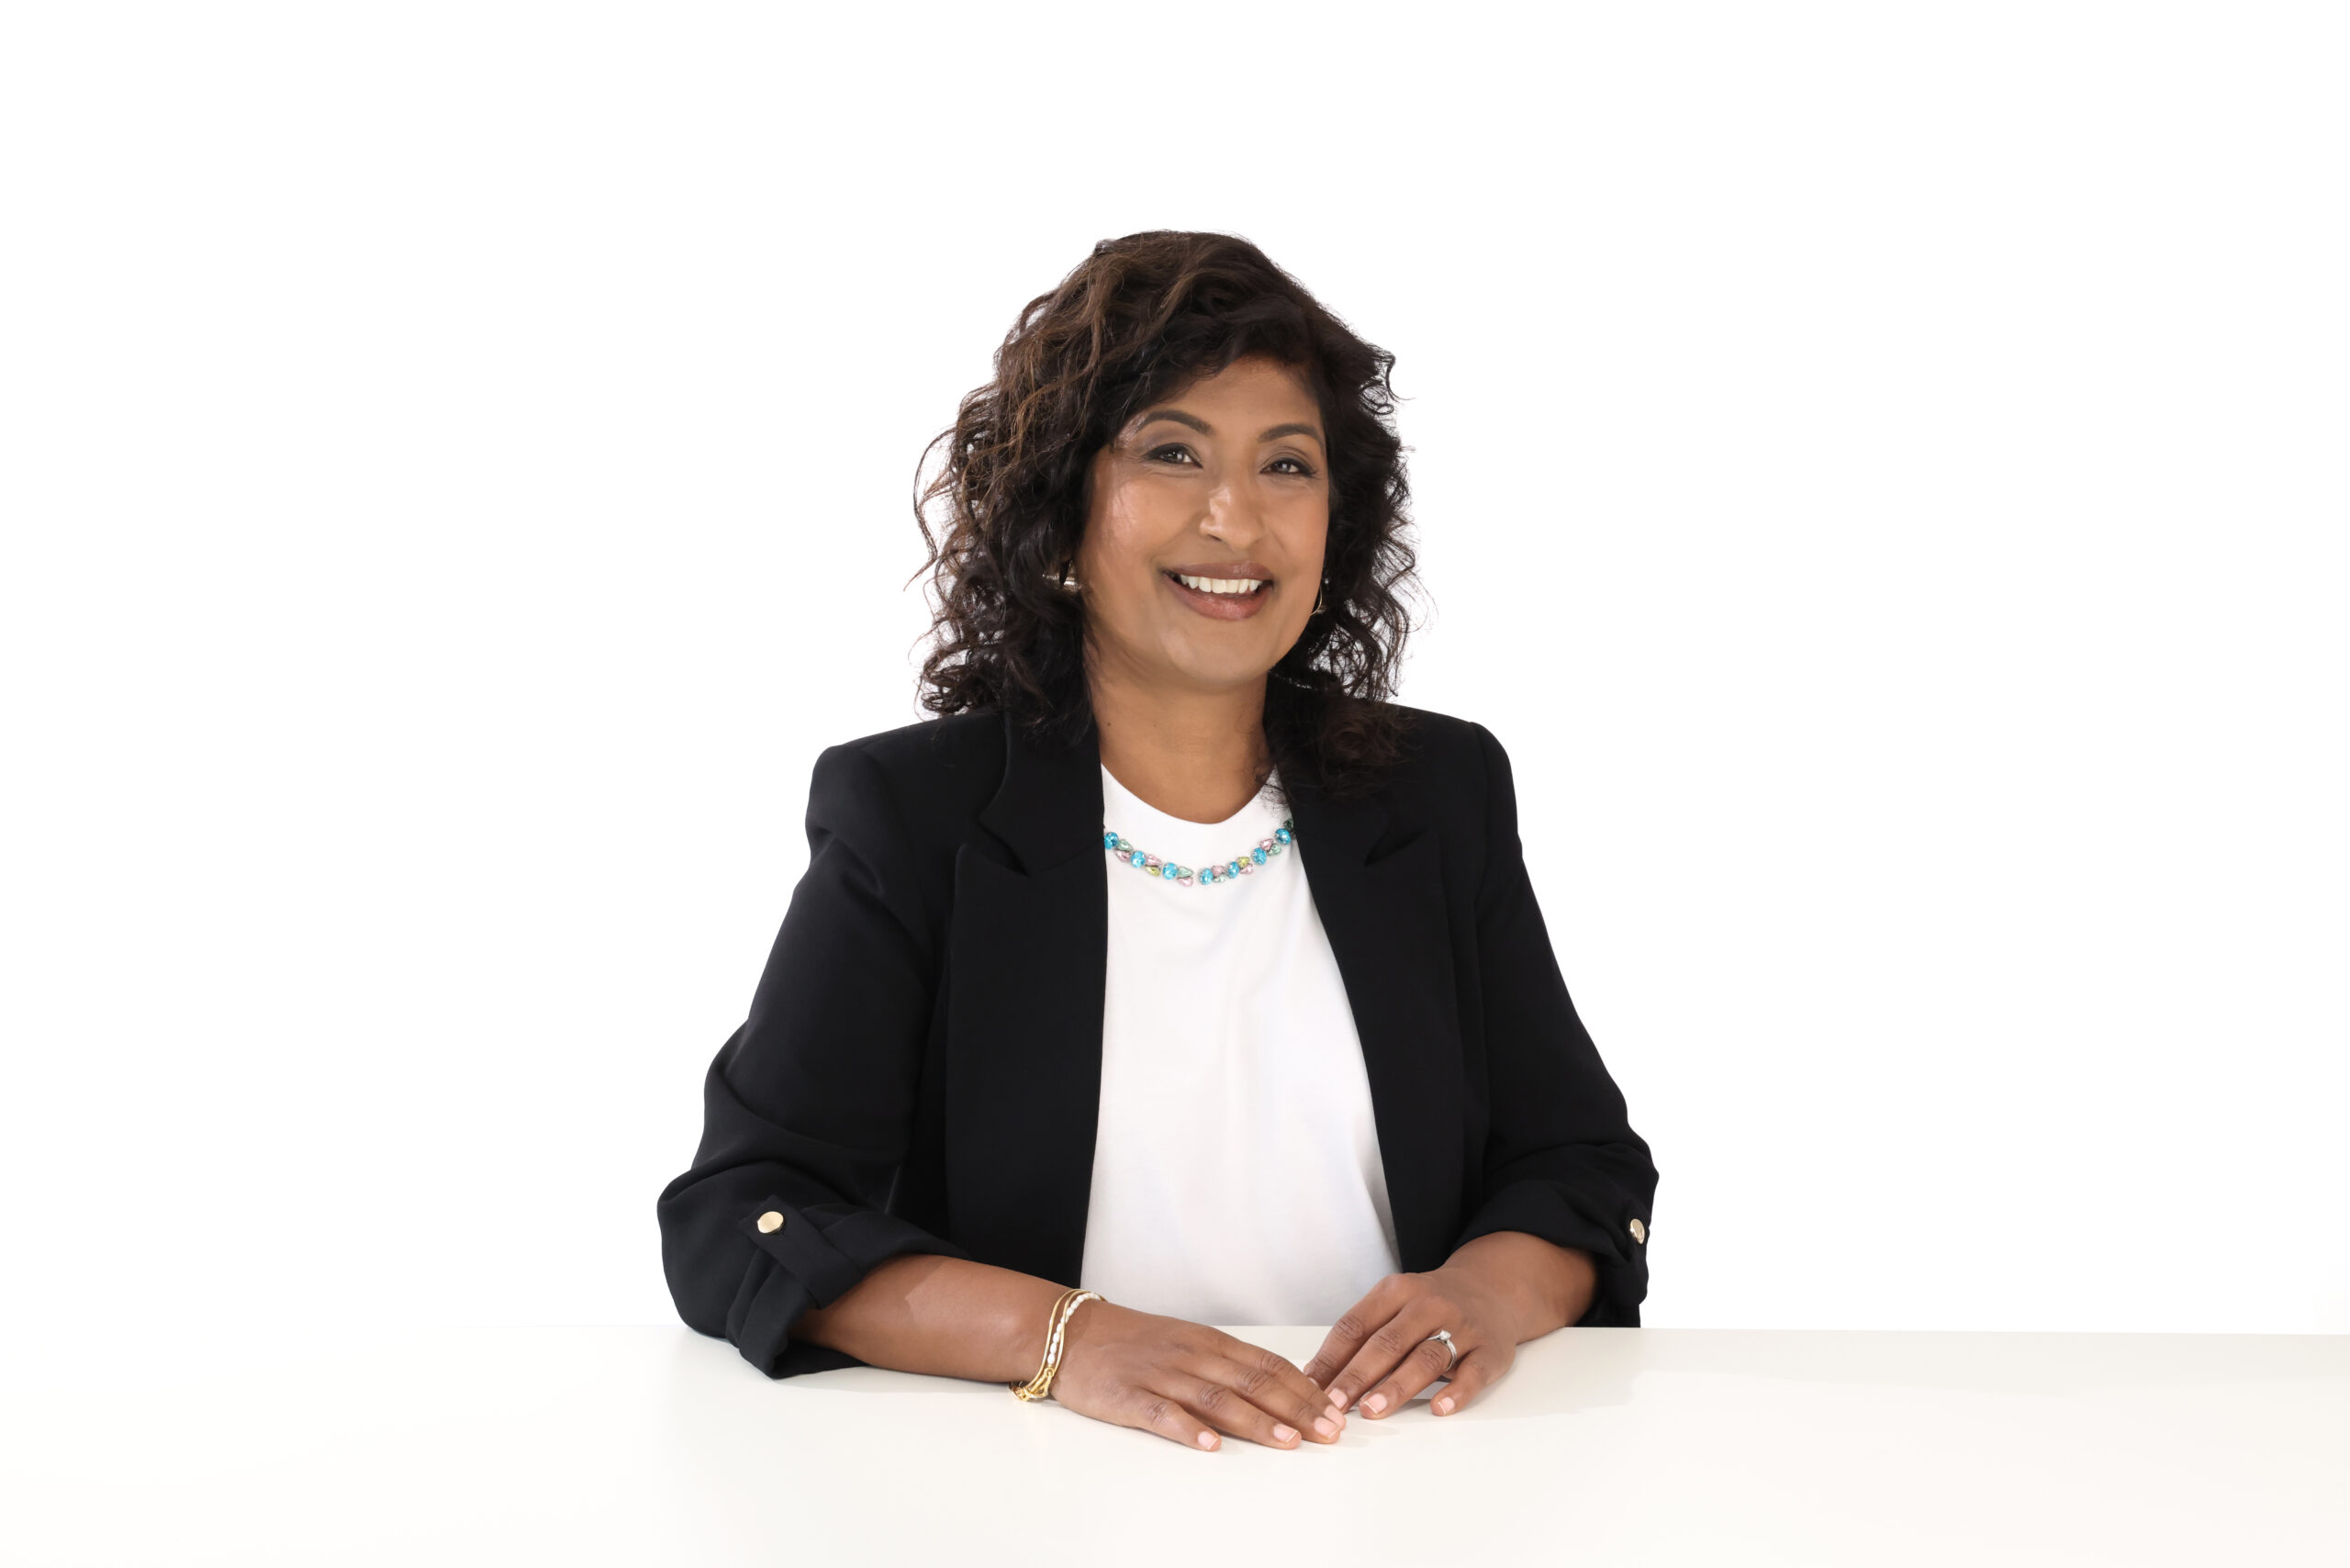
Rakhee Wood is an Independent Financial Adviser at Butterfly Financial Planning in Bromley, Kent
Taking a bonus without thinking about the tax impact
Bonuses can feel like a straightforward cash boost, but at this income level, they can have a much bigger knock-on effect than people expect.
A bonus can push income further into the Personal Allowance taper range, which means a larger portion of earnings gets taxed at a higher effective rate.
Without planning, the net amount received can feel surprisingly low compared with the headline figure. In some cases, making pension contributions or utilising salary sacrifice before the bonus is paid can improve the overall tax position, but this needs to be considered in advance rather than after the money has landed.
Assuming a higher salary means proportionately more take-home pay
A pay rise above £100,000 does not translate into a simple increase in monthly disposable income.
Higher earnings can reduce your Personal Allowance and push more income into higher tax, so the jump in take-home pay can look smaller than expected.
The practical step is to compare your old and new payslips line by line, including your tax code and any pension or salary sacrifice deductions, so you can see exactly what has changed.
Accidentally losing childcare benefits
Many families do not realise that crossing the £100,000 threshold can have consequences beyond income tax as it can result in the immediate loss of eligibility for the Tax-Free Childcare scheme and the 30 hours of free childcare entitlement for three- and four-year-olds in England.
The withdrawal of these benefits can be worth several thousand pounds annually, leaving some families facing significantly higher childcare costs despite only marginally higher incomes.
Not understanding how tax thresholds reduce real income over time
Frozen thresholds and rising salaries can combine to pull more people into higher tax exposure over time, a process often referred to as fiscal drag.
As earnings increase, more of the income can be pushed into higher tax bands, even when lifestyle and spending remain the same. Many people understand that pensions can help manage this, but hesitate to act because they do not want to lock money away or feel unsure about how pensions work in practice.
The result is a lack of planning at exactly the point where small adjustments could make a meaningful difference.
A clearer approach, such as putting together all of your income, tax, pension options and anticipated regular and planned household expenditure, helps you to see both the immediate tax impact and the longer-term outcome, so decisions feel more informed.