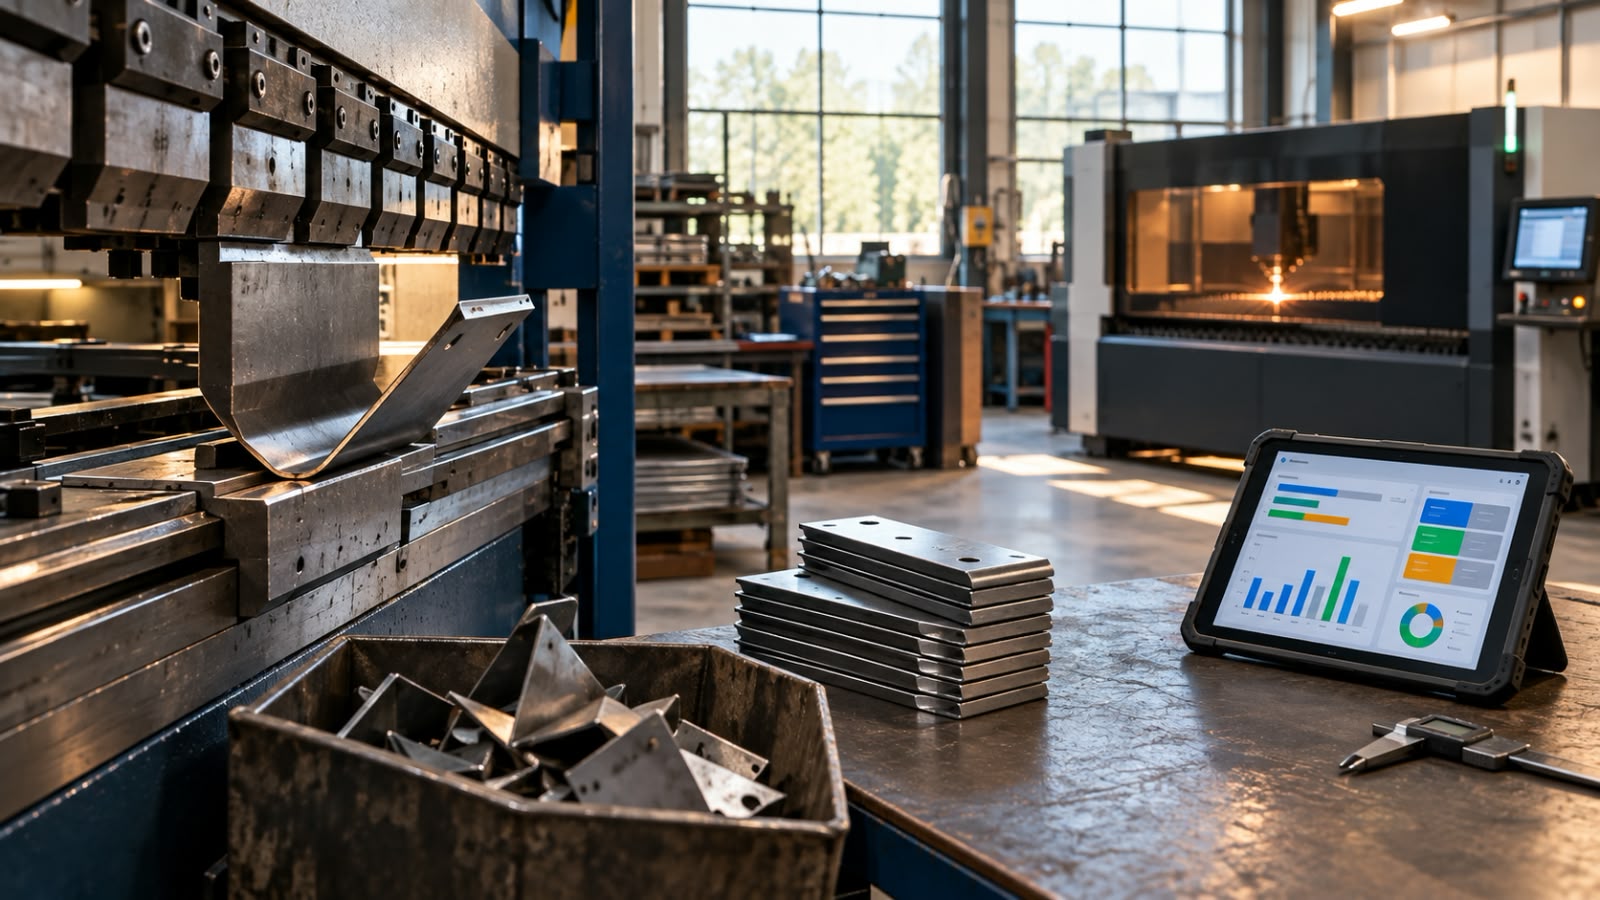
Job costing in manufacturing assigns every direct cost — material, machine time, labour and scrap — to a single work order, so each job carries its own margin instead of vanishing into a monthly total. Most small UK manufacturers get material right, because material arrives with a purchase invoice attached. Machine time, shop-floor labour and scrap are harder to see, and they are where margin quietly leaks. Job costing software exists to capture those three as they happen, against the job that caused them.
The three costs that decide whether a job made money
Material cost behaves well. A supplier sends an invoice, the invoice carries a job reference, and the number lands in the right place. Machine time, labour and scrap behave badly, and each fails for a different reason.
Machine time is an internal cost with no invoice behind it, so a shop that never sets a machine hour rate charges the customer for nothing at all. Labour is recorded in hours by people whose job is production, not administration. Scrap is a loss nobody enjoys writing on a job card, so it gets absorbed into the next batch instead.
A job quoted at 31% gross margin can land at 24% through those three alone, without a single supplier raising a price. The fix is not tighter buying. The fix is measuring what the job actually consumed.
Costing machine time
Building a machine hour rate
A machine hour rate is the annual cost of owning and running one machine divided by the hours that machine actually runs. The annual cost includes depreciation or finance payments, electricity, compressed air, consumables and tooling, planned maintenance, and a share of the floor space the machine occupies.
Take a £120,000 press brake financed over five years. Finance costs roughly £24,000 a year. At 11 kW and 25p per kWh across 1,600 running hours, electricity adds about £4,400. Maintenance runs £3,000, tooling £2,000, and floor space carries £1,500. The total of £34,900 over 1,600 hours gives a rate near £22 an hour. A fibre laser with higher capital cost, assist gas and consumable optics sits closer to £34.
Setting a rate per machine, rather than one blended shop rate, is the difference between a quote that reflects the process and a quote that averages your best machine with your worst. It is worth working the calculation through for each asset rather than copying one figure across the shop.
Setup, changeover and idle time
Setup is a cost of the job, not a cost of the day. A 20-minute changeover spread across 500 parts adds under three seconds to each one; the same changeover across 20 parts adds a full minute per part. Short runs carry setup heavily, which is exactly why small batches quoted on cycle time alone lose money.
Idle machine hours belong in the divisor, not the numerator. Charging a job for the hours a machine sat waiting for material inflates that job and flatters the next one. Low utilisation raises the hourly rate across every job instead, which is the honest signal: the machine costs the same whether it cuts or waits.
Costing shop-floor labour
Direct hours and indirect hours
Direct labour is time booked to a work order: cutting, folding, welding, assembling, inspecting, packing. Indirect labour is time the shop needs, but no single job caused: sweeping, stock counts, toolbox talks, waiting for a drawing. Both are real costs. Only the first belongs on the job card; the second sits in overhead and gets recovered through the rate.
The trouble starts when the split is guessed at the end of the week. A welder who worked three jobs on Tuesday remembers two of them by Friday, and the third job looks more profitable than it was. Daily booking against the work order is what keeps labour costing honest.
Why the pay rate is not the cost rate
A £14 hourly wage does not cost £14 an hour. Employer’s National Insurance, pension auto-enrolment, holiday pay, statutory sick pay, protective equipment and training all attach to that person. Spread the cost over productive hours rather than paid hours (a full-time operator loses around 230 hours a year to holiday and bank holidays before any absence), and £14 becomes closer to £19.
Quoting at the wage rate therefore understates labour by roughly a quarter of its true cost. On a job with 26 hours of shop-floor work, that is £130 of margin gone before anyone touches a machine. The burdened labour cost calculation needs doing once a year, per grade, and then applying everywhere.
Costing scrap, rework and waste
Scrap allowance against actual scrap
Every estimator builds in a scrap allowance: 3% on sheet metal, more on castings or first-off machined parts. The allowance is a prediction. Actual scrap is a fact, and the gap between the two is material variance.
Scrap recorded at the moment it happens tells you which job, which machine and which operation produced it. Scrap absorbed into a stock count tells you nothing except that the material has gone. A shop running 8% actual scrap against a 3% allowance is losing 5% of material value on every job, and quoting the next one as though it will not happen again.
Rework is charged twice
Rework consumes labour and machine time a second time, on parts already paid for once. A batch of 200 brackets with 12 requiring re-drilling picks up a fresh setup, three hours of shop-floor time, and a second trip to the powder coater. None of that sits in the original estimate.
Rework also hides well. The parts ship, the customer is satisfied, the job closes as complete, and the cost shows up only as a margin that came in light for no obvious reason. Booking rework to its own cost code separates a pricing problem from a quality problem, which are fixed in entirely different ways.
Putting the three together on one job
Consider a 200-off laser-cut and folded bracket, quoted at £3,600. The estimate carries £1,150 of sheet, seven laser hours at £34, five press-brake hours at £22, 26 hours of deburring and assembly at £19, and £480 of subcontract powder coating. Planned cost comes to £2,472 and planned margin to 31%.
The job runs. Actual scrap reaches 8% rather than 3%, so 16 parts are scrapped instead of the six allowed for, adding sheet, laser and brake time for ten extra parts and a second coating charge, roughly £160. Two changeovers go unbooked because the operator moved straight onto the next order, hiding about £40 of machine time. Twelve parts need re-drilling, costing three hours of labour and a short brake setup, near £70. Nobody has made a mistake worth a disciplinary, and nobody has bought anything badly.
Actual cost lands at £2,742 and margin at 24%. The seven-point drop came entirely from machine time, labour and scrap, and every pound of it was visible on the day it happened.
Why the numbers usually go missing
Small manufacturers rarely lack the will to cost jobs properly. They lack a route for the data. Paper job cards sit in a tray until someone types them up. Timesheets arrive a week late and get rounded to the nearest half day. Scrap goes in a skip without a job number. The costing spreadsheet holds last quarter’s rates because updating it takes an afternoon nobody has.
By the time the true cost of a job is known, the job has shipped, the next three have been quoted on the same flawed assumptions, and the pattern repeats. That delay, rather than the arithmetic, is the reason moving off job costing spreadsheets changes the outcome.
A costing process a small factory can actually run
Six habits cover most of the gap, and none of them needs a dedicated cost accountant.
- Set cost codes for material, machine time, direct labour, subcontract, and scrap, and use the same five on every work order.
- Fix a machine hour rate per machine and a burdened rate per labour grade, review both annually, and quote from nothing else.
- Book time daily against the work order, including setup, and keep indirect time in its own bucket.
- Record scrap and rework at the point they happen, with the job, operation, and reason.
- Compare committed and actual cost against budget weekly while the job is still open and recoverable.
- Hold a ten-minute review on every completed job, and feed what it shows back into the next estimate.
Built into a system rather than a spreadsheet, these habits produce a live cost per job, and the shop floor only has to book what it did.
Frequently asked questions
Does a small manufacturer need job costing software?
Usually, once several jobs run through the same machines at the same time. Shared resources make it impossible to tell by eye which job consumed what, and a spreadsheet updated after the fact reports history rather than a position you can still act on.
Is scrap a direct cost?
Yes, when it is traceable to a job. Scrap produced on a specific work order belongs to that order at full material and processing value. Unattributable waste goes to overhead and comes back through the machine and labour rates.
Should idle machine time be charged to a job?
No. Idle hours reduce the hours a machine runs, which raises its hourly rate for every job. Charging idle time directly penalises whichever job happened to be open when the machine stopped.
Can a spreadsheet handle job costing for a small factory?
Yes, for a handful of live jobs and one or two machines. Beyond that, the reconciliation between timesheets, purchase invoices and scrap records takes longer than the jobs allow, and the numbers fall behind the work.
Summary
Accurate job costing in a small manufacturing business rests on three rates set once a year and three inputs captured daily. The rates are a machine hour rate per asset, a burdened labour rate per grade, and a realistic scrap allowance per process. The inputs are hours booked to the work order, machine time including setup, and scrap and rework recorded as they occur. Get those six things right and every completed job tells you something usable about the next quote.