The Chancellor’s first Budget had some targeted support for small businesses must most of the announcements focused on future modernisation. ACCA warns that predictable costs, simpler tax rules and effective public services will be essential to restoring confidence.
The Chancellor’s first Budget has offered some limited announcements for businesses facing persistent cost pressures, but the feedback from our businesses is that the measures announced may not be enough to deliver the certainty SMEs need to invest and grow.
That is the central message from ACCA (the Association of Chartered Certified Accountants), which has welcomed elements of the Budget while warning that the cumulative impact of employment costs, tax compliance and changes to local decision-making will ultimately shape business confidence.
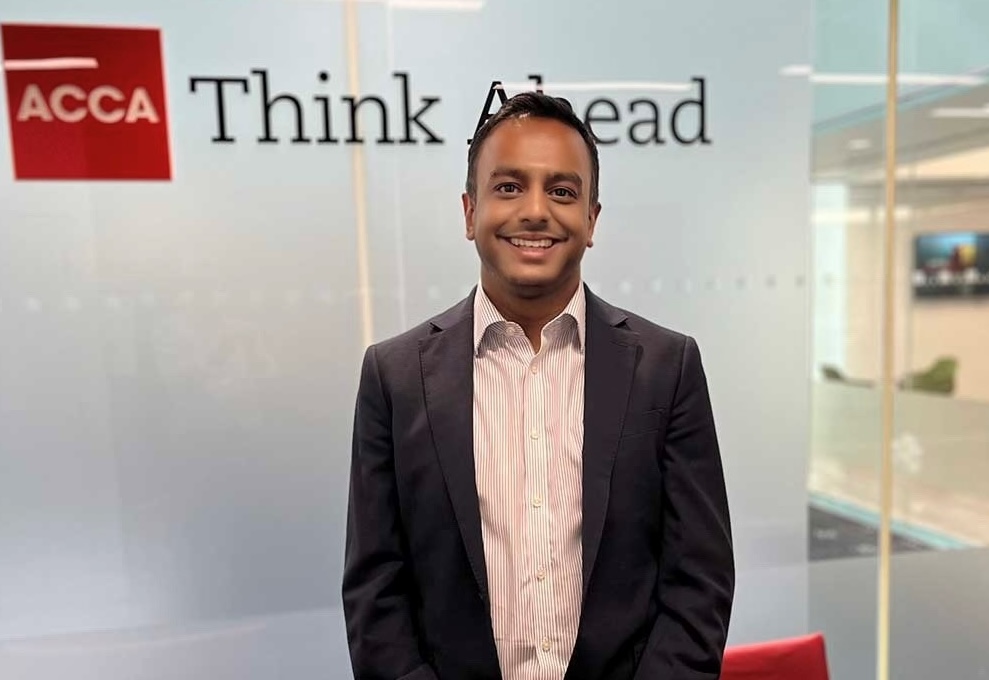
Abdul Goffar, UK Director of ACCA, said:
“ACCA’s message following the Budget is that the quality of the announcements matters as much as the amount raised.”
He added: “Businesses need stability to improve confidence and encourage investment. HMRC needs the capacity to collect what is owed and tax reform should simplify the system – rather than add another layer of complexity.”
Employment costs remain a key concern
There was no employment cost relief with thresholds remaining frozen. Among the Budget announcements was a 3.9% increase in the National Living Wage and National Minimum Wage. While higher wages support workers’ incomes, they also increase payroll costs for employers, particularly those operating in labour-intensive sectors.
The implications extend beyond the headline wage rate. Employers must also consider associated costs, including employer National Insurance contributions, pension contributions and the time required to administer payroll and comply with employment regulations.
These pressures can influence decisions about hiring, training, and expansion. For businesses already working with tight margins, even a relatively modest increase in one cost can become difficult to manage when combined with higher supplier prices, rent and financing costs.
The challenge for policymakers is therefore to balance improving workers’ living standards with creating conditions in which businesses can continue to remain financially sustainable.
Business rates relief offers targeted support
The Budget raised the threshold for small business rates relief a welcome increase for many small businesses from £12,000 to £18,000.
Business rates are a high fixed cost for many firms with physical premises. Unlike expenditure that can be reduced quickly when trading slows, property-related costs can be difficult to adjust, adding additional pressure on businesses experiencing fluctuations in customer demand. Increasing the relief threshold could help eligible businesses manage their overheads and retain more working capital.
However, the practical benefit will depend on the detailed rules, eligibility criteria and how the changes interact with individual businesses’ rateable values and existing relief arrangements.
Targeted relief can help address immediate pressures, but it does not necessarily resolve wider concerns about the long-term cost of operating commercial premises.
For ACCA, the broader question is whether measures such as these translate into sustained improvements in confidence. Short-term assistance can ease financial pressure, but investment decisions are more likely to follow when businesses can forecast costs over several years.
Fiscal devolution brings opportunities and uncertainty
Another significant element of the Budget is the commitment to allow 100% of business rates to be retained locally by the end of the decade. The plans also provide for mayors to receive 20% from next year, alongside a share of income tax from 2028.
Fiscal devolution could give local leaders greater scope to shape economic development around regional priorities. Decisions about transport, skills, regeneration and local infrastructure can have a direct bearing on business productivity, recruitment and access to customers.
Devolution, however, also raises questions about accountability. Businesses operating across council or mayoral boundaries may need to navigate different priorities, processes and approaches to local economic policy.
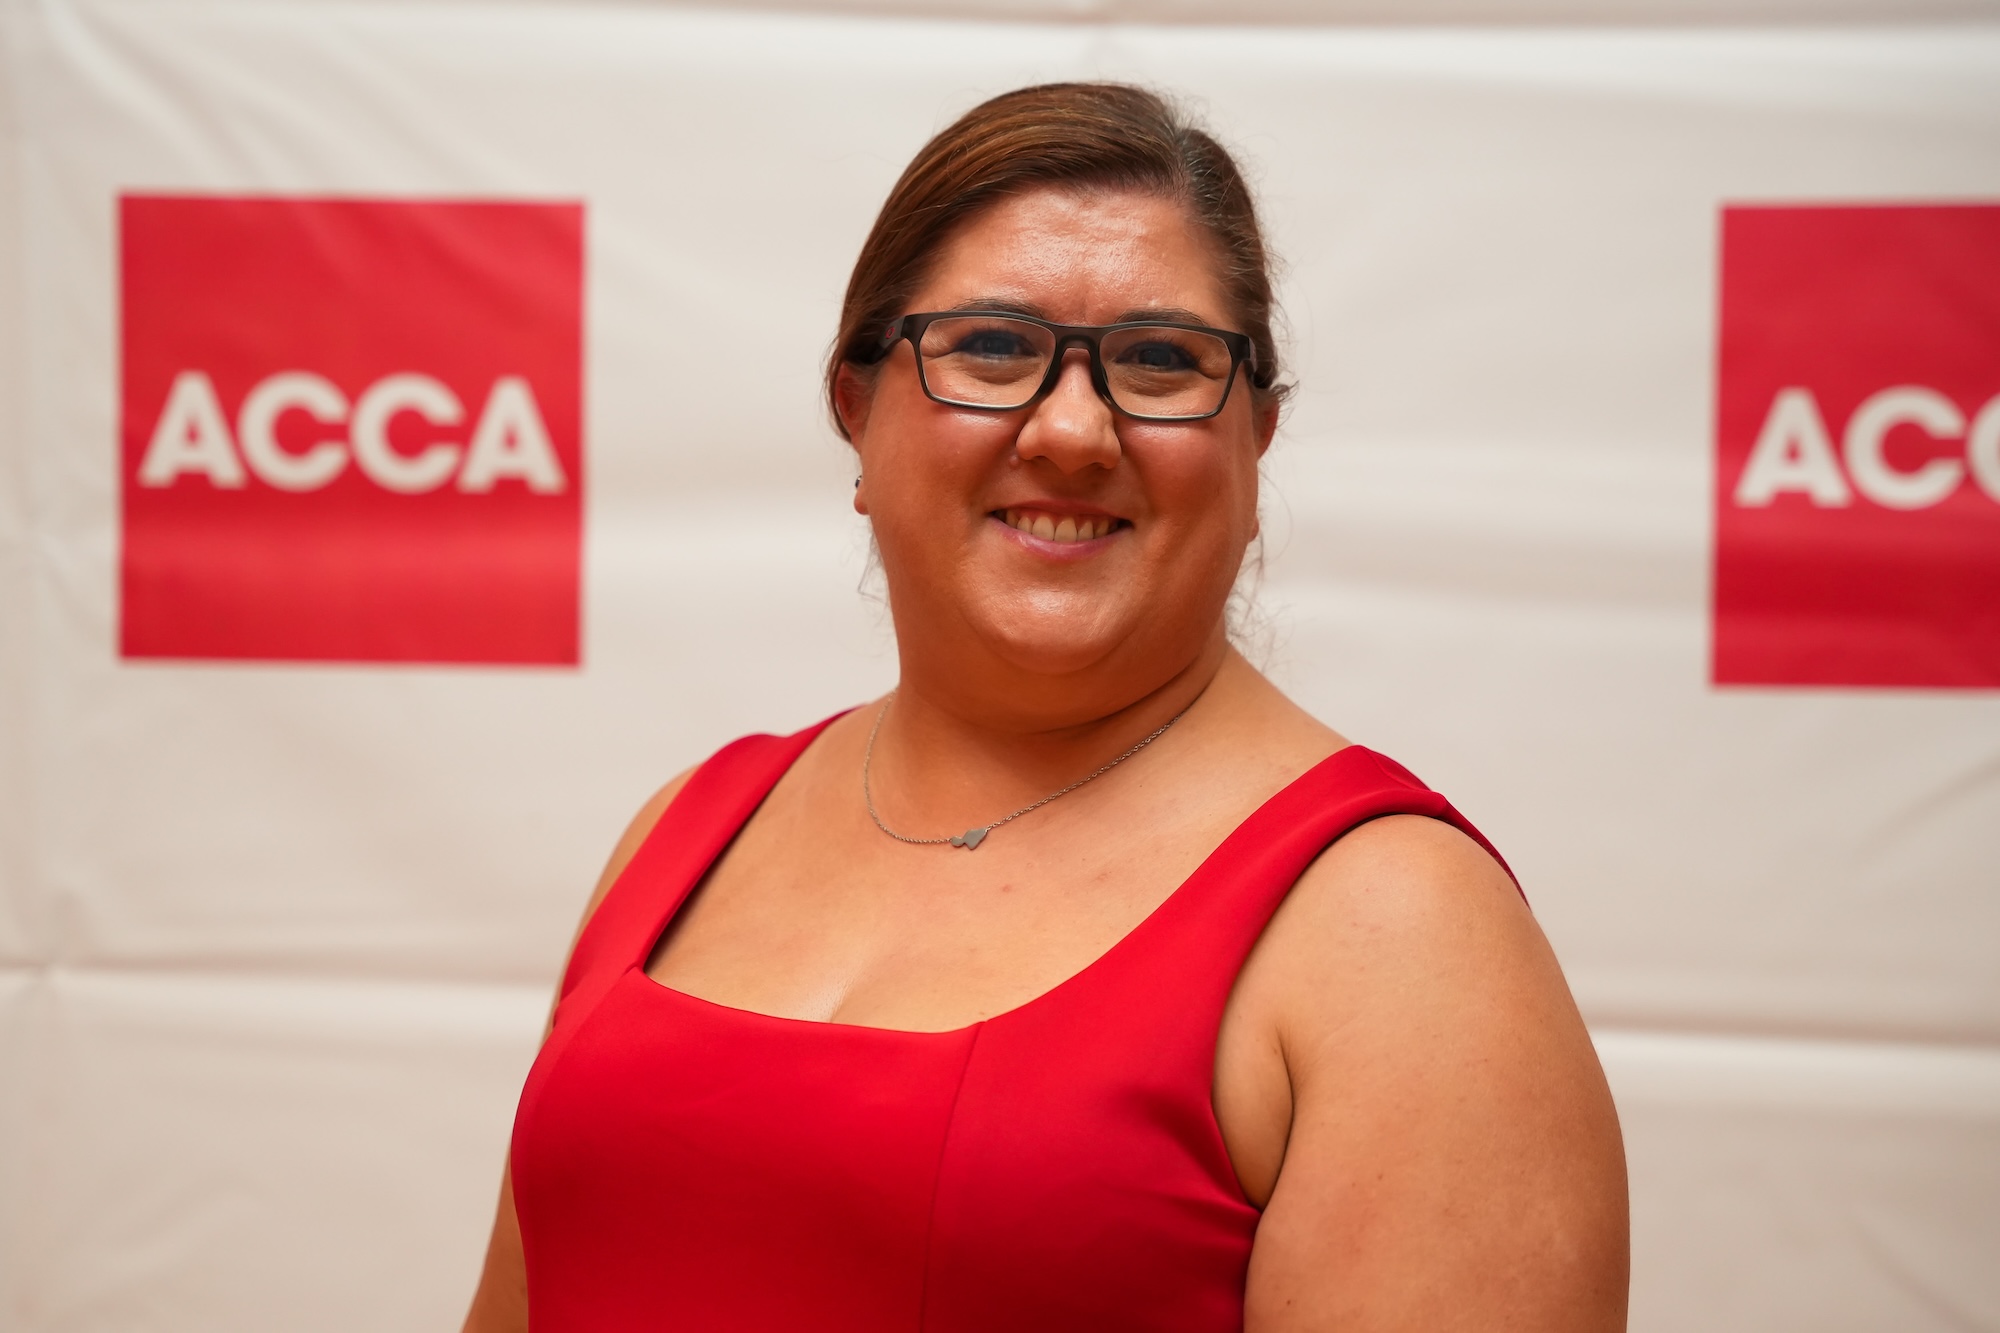
Gemma Gathercole, Strategic Engagement Lead for ACCA, said:
“Devolution brings decision-making closer to communities, but it must be accompanied by clear accountability, transparent public finances and adequate finance expertise at local level.”
For businesses, the success of fiscal devolution will depend on the clarity of the proposed framework and how effectively local authorities implement it.
HMRC reform must improve the taxpayer experience
The Budget’s commitments to invest in HMRC, improve compliance and strengthen the collection of overdue tax were also welcomed by ACCA.
An effective tax administration system is important both for public finances and for businesses that need timely, reliable guidance to meet their obligations. Improving compliance can help ensure that businesses operating within the rules are not disadvantaged by others failing to pay what they owe.
However, stronger enforcement must be accompanied by sufficient staffing, appropriate technology and significantly improved service levels from HMRC for compliant taxpayers. And their Accountants Glenn Collins, Head of Technical and Strategic Engagement at ACCA, said investment in HMRC was needed, but stressed that new measures would only work if the department had the resources, systems and a clear implementation plan.
He also highlighted the importance of improving the handling of routine tax administration, including where HMRC had made errors, providing timely guidance and making appropriate use of artificial intelligence. Professional accountants and tax agents, he argued, could help ease pressure on HMRC if they were enabled to undertake more tax-related tasks.
The objective should be a tax system that is easier to understand and comply with, while maintaining effective enforcement. Simplification and better service delivery would help businesses manage their responsibilities with greater confidence.
A challenging fiscal outlook
The Budget also reflects the wider constraints facing the UK economy. The government is seeking to provide some relief to households and businesses while managing public debt, raising sufficient revenue and maintaining confidence in the public finances.
ACCA Chief Economist Jonathan Ashworth described the Budget as a “do no harm” Budget, with relatively small measures intended to provide breathing space amid significant economic pressures.
Certainty will determine whether businesses invest
Taken together, the Budget’s measures offer some targeted support and set out longer-term modernisation ambitions for tax administration and local government finance. But their effect on business confidence is questionable and will depend on how clearly and consistently they are implemented.
For SMEs, confidence is built through a combination of manageable costs, predictable policy, accessible public services and confidence that investment made today will remain viable tomorrow. One-off relief may help businesses absorb immediate pressures, but it cannot substitute for a stable operating environment.
Feature image by cottonbro studio from Pexels