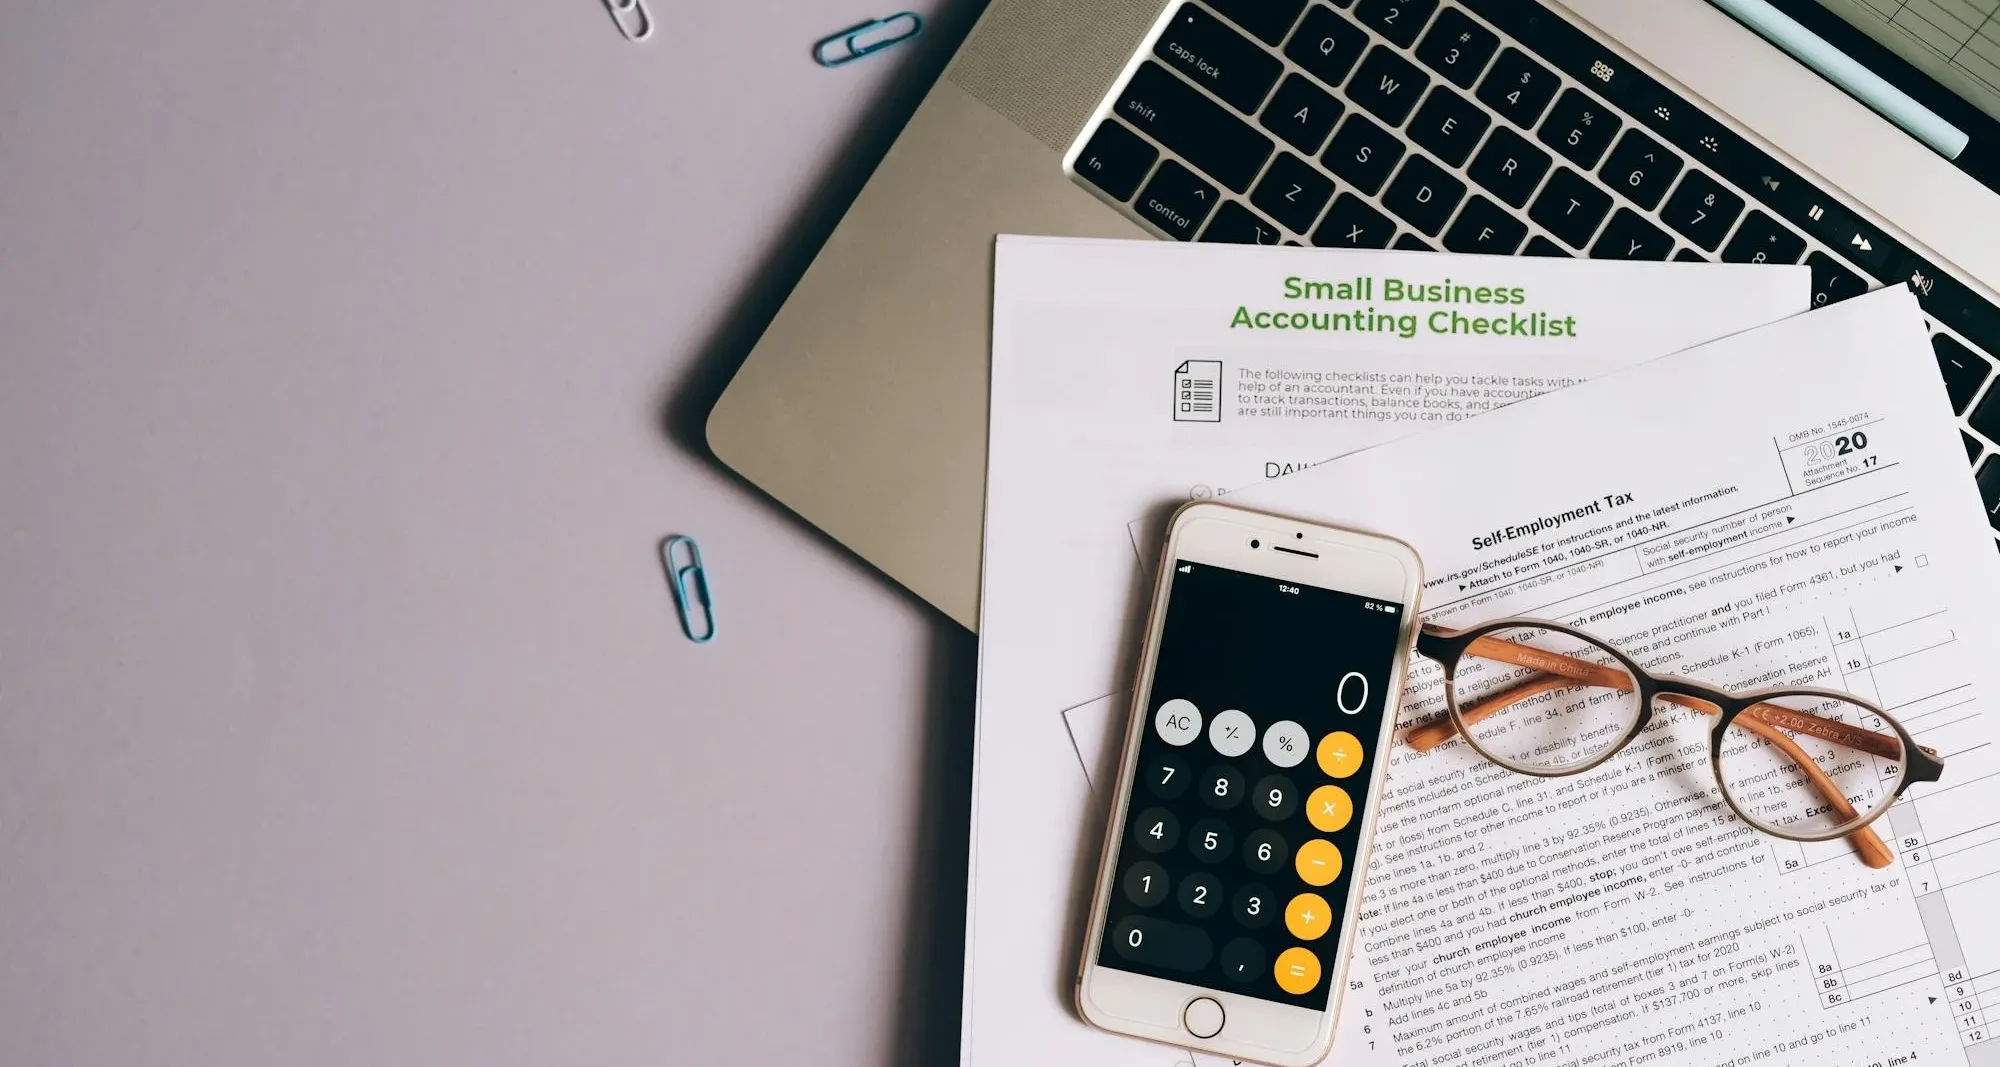
Starting a business in 2025 is full of opportunities—but it’s also a time of complex regulations, new compliance rules, and increasing financial pressure. That’s why laying the right accounting foundations from day one is essential.
Whether you’re launching a consulting firm, online store, or creative agency, this startup-focused checklist will help you stay financially organised and ready to grow.
1. Choose the Right Legal Structure
Your legal structure affects your taxes, liability, and ability to attract investment.
- Sole trader: Quick setup, minimal paperwork, but full personal liability.
- Limited company: Offers better protection and tax advantages, with added reporting duties.
Most UK startups opt for a limited company structure, especially when planning for long-term growth or hiring employees
Small business specialists Fusion Accountants based in London offer expert support to ensure you’re making the right decision for your business model.
2. Register with HMRC or Companies House
Making your business official depends on its structure.
- Sole traders register with HMRC for Self Assessment. It’s free and takes just a few minutes online.
- Limited companies must register with Companies House, which involves:
- Appointing directors
- Allocating shares
- Providing a registered address
- Creating Articles of Association
You’ll also need to register for Corporation Tax and receive your Unique Taxpayer Reference (UTR). Getting this step right from the start will save you from costly rework later.
3. Open a Business Bank Account
Using your personal bank account may seem convenient, but it quickly causes confusion when managing finances.
With a business bank account, you can:
- Keep finances separate for clearer records
- Link directly to your accounting software
- Simplify bookkeeping and HMRC compliance
Many digital-first banks like Starling and Tide offer accounts specifically designed for small business owners—with low fees, instant notifications, and powerful integrations.
4. Select the Right Accounting Software
Spreadsheets won’t cut it once your business is off the ground. You’ll need cloud-based software that helps you:
- Issue and track invoices
- Monitor cash flow
- Manage expenses and VAT
- File returns under Making Tax Digital (MTD)
Top options include:
- Xero – powerful for automation and scalable businesses
- QuickBooks – user-friendly and popular among SMEs
- FreeAgent – built for freelancers and micro-businesses
Choosing the right tool now will help you avoid costly transitions later as your business grows.
5. Understand VAT and Registration Thresholds
Many startups think VAT doesn’t apply to them—but that’s a mistake.
- Compulsory registration is triggered once turnover exceeds £85,000 in a 12-month rolling period.
- Voluntary registration can benefit those buying expensive equipment or working with VAT-registered clients.
You’ll also need to choose a scheme:
- Standard VAT lets you reclaim VAT on most expenses.
- Flat Rate Scheme simplifies calculations but limits reclaim options.
- Cash Accounting delays payment until invoices are paid—ideal for cash flow management.
An accountant can help you choose the scheme that best suits your needs.
6. Track Every Expense from Day One
Good financial habits start early. Keep a record of every business expense—including software subscriptions, equipment, advertising, and mileage.
Why it matters:
- Reduces your tax bill through deductions
- Provides visibility into spending patterns
- Prepares you for quarterly or annual reviews
Most accounting software lets you snap receipts, tag transactions, and generate reports instantly.
7. Work With an Accountant Who Knows Startups
The right accountant can make or break your startup’s financial success. More than just filing tax returns, they offer strategic guidance on:
- Business structuring
- Tax efficiency
- Payroll and pensions
- Navigating HMRC communications
Find someone who understands startups and offers proactive advice—not just year-end paperwork. It’ll save you time, money, and a lot of stress.
Bonus Tips for 2025 Success
- Open a savings account dedicated to tax and VAT liabilities—this prevents surprises during payment season.
- Use software reminders to track Companies House filings, VAT returns, and Self Assessment deadlines.
- Schedule quarterly check-ins with your accountant to review profit margins, forecasts, and opportunities.
- Plan your budget monthly—cash flow, not profit, keeps your business alive.
Final Thoughts
Starting a business in 2025 comes with its fair share of challenges—but with a smart accounting setup, you’ll avoid the most common pitfalls.
Small business specialists Fusion Accountants based in London have helped thousands of founders structure their businesses, stay compliant, and grow sustainably. They’re ready to help you launch with clarity and confidence.