A white-label sportsbook can reduce launch time, lower early execution pressure, and simplify market entry. That is exactly why so many operators are drawn to it. In the UK market, though, the more important question is not how quickly a platform can go live. It is what the operator gives up in return.
That includes control over compliance workflows, payment flexibility, reporting depth, product changes, and long-term commercial freedom. In a market where accountability matters as much as speed, launch convenience alone is not enough.
The real issue with white-label is not that the model is flawed by default. The issue is that buyers often weigh ease too heavily and structure too lightly. Operators usually discover the real shape of the arrangement later, when the first non-standard request runs into the provider’s roadmap, approved vendors, reporting logic, or contract terms.
That is why this decision should be treated less like a quick route to market and more like an operating model choice.
Why White Label Still Appeals to Operators
White label remains attractive for sensible reasons.
It shortens the distance between decision and launch. Odds feeds, payment tools, front-end flows, back-office access, and core operational components often arrive as part of one package. For operators under timeline pressure, that can be commercially valuable. A new season, a market window, or a fast entry strategy can make speed matter in a very real way.
It also reduces the early burden on internal teams. Not every operator wants to carry full platform design, integrations, and infrastructure decisions from day one. For businesses entering the market with limited in-house technical depth, the appeal is obvious. There is less build complexity, less early operational overhead, and less need to assemble every layer independently.
Many buyers start their evaluation by focusing on launch speed first instead of properly comparing the long term fit of different sports betting platform solutions.
The problem is that white label does not only delivers speed. It also brings a predefined operating structure. The wallet works the way the provider designed it to work. Reporting follows the provider’s back office logic. Integrations fit within the provider’s ecosystem. Operators who suit that model can benefit from it. Operators who grow beyond it often discover that the convenience they bought at launch has become the constraint they now have to manage.
Why the UK Market Makes This Decision More Sensitive
This decision becomes more delicate in the UK because supplier relationships are not just commercial arrangements. They also shape how responsibility works in practice.
When payments fail, reporting lacks depth, a compliance workflow needs adjustment, or an incident crosses multiple vendors, the operator still needs clear ownership, timely answers, and workable control. That is where weaker white label decisions become more expensive. They create blurred accountability at exactly the point where clarity matters most.
In a market like the UK, that is not a small issue. Operators need a setup that supports more than the happy path. They need something that holds up when documentation is needed quickly, when reporting must be trusted, and when workflows must adapt without turning every change into a vendor dependency.
The more tightly regulated and commercially mature the market, the less room there is for platform relationships that are easy to buy but difficult to operate inside.
The Operating Questions Buyers Ask Too Late
Most operators spend too much time comparing product surfaces and not enough time understanding how control is actually distributed after launch.
Who controls the license relationship in practice?
Who owns the reporting logic?
Who decides which payment methods can be added?
Who can change operational workflows without waiting for provider prioritisation?
Who handles escalation when an issue touches platform, payments, and support at the same time?
These are not side questions. They define whether the operator is running the business with real authority or simply operating inside a structure that someone else controls.
Many white-label arrangements become more restrictive than they first appear. During the sales process, the model can look flexible enough. Once live, operators often realise that flexibility exists only inside approved boundaries. Anything more meaningful becomes a provider request, a commercial discussion, or a scoped change with its own delay and cost.
That is usually the point at which some operators start realising that working with a sports betting app development company may offer more long-term freedom, even if it requires more commitment at the start.
Where White Label Sportsbook Providers Usually Create Friction
Friction rarely appears all at once. It usually shows up as recurring operational drag.
Payments and cashier flexibility
One of the first pressure points is usually payments. An operator wants to support a market-specific payment method, refine withdrawal handling, or adapt cashier logic to a commercial need. The request goes to the provider. The provider evaluates it against their roadmap or existing integrations. The operator waits.
Nothing fails in a dramatic sense. But the platform stops moving at the speed the business needs.
Back office and reporting depth
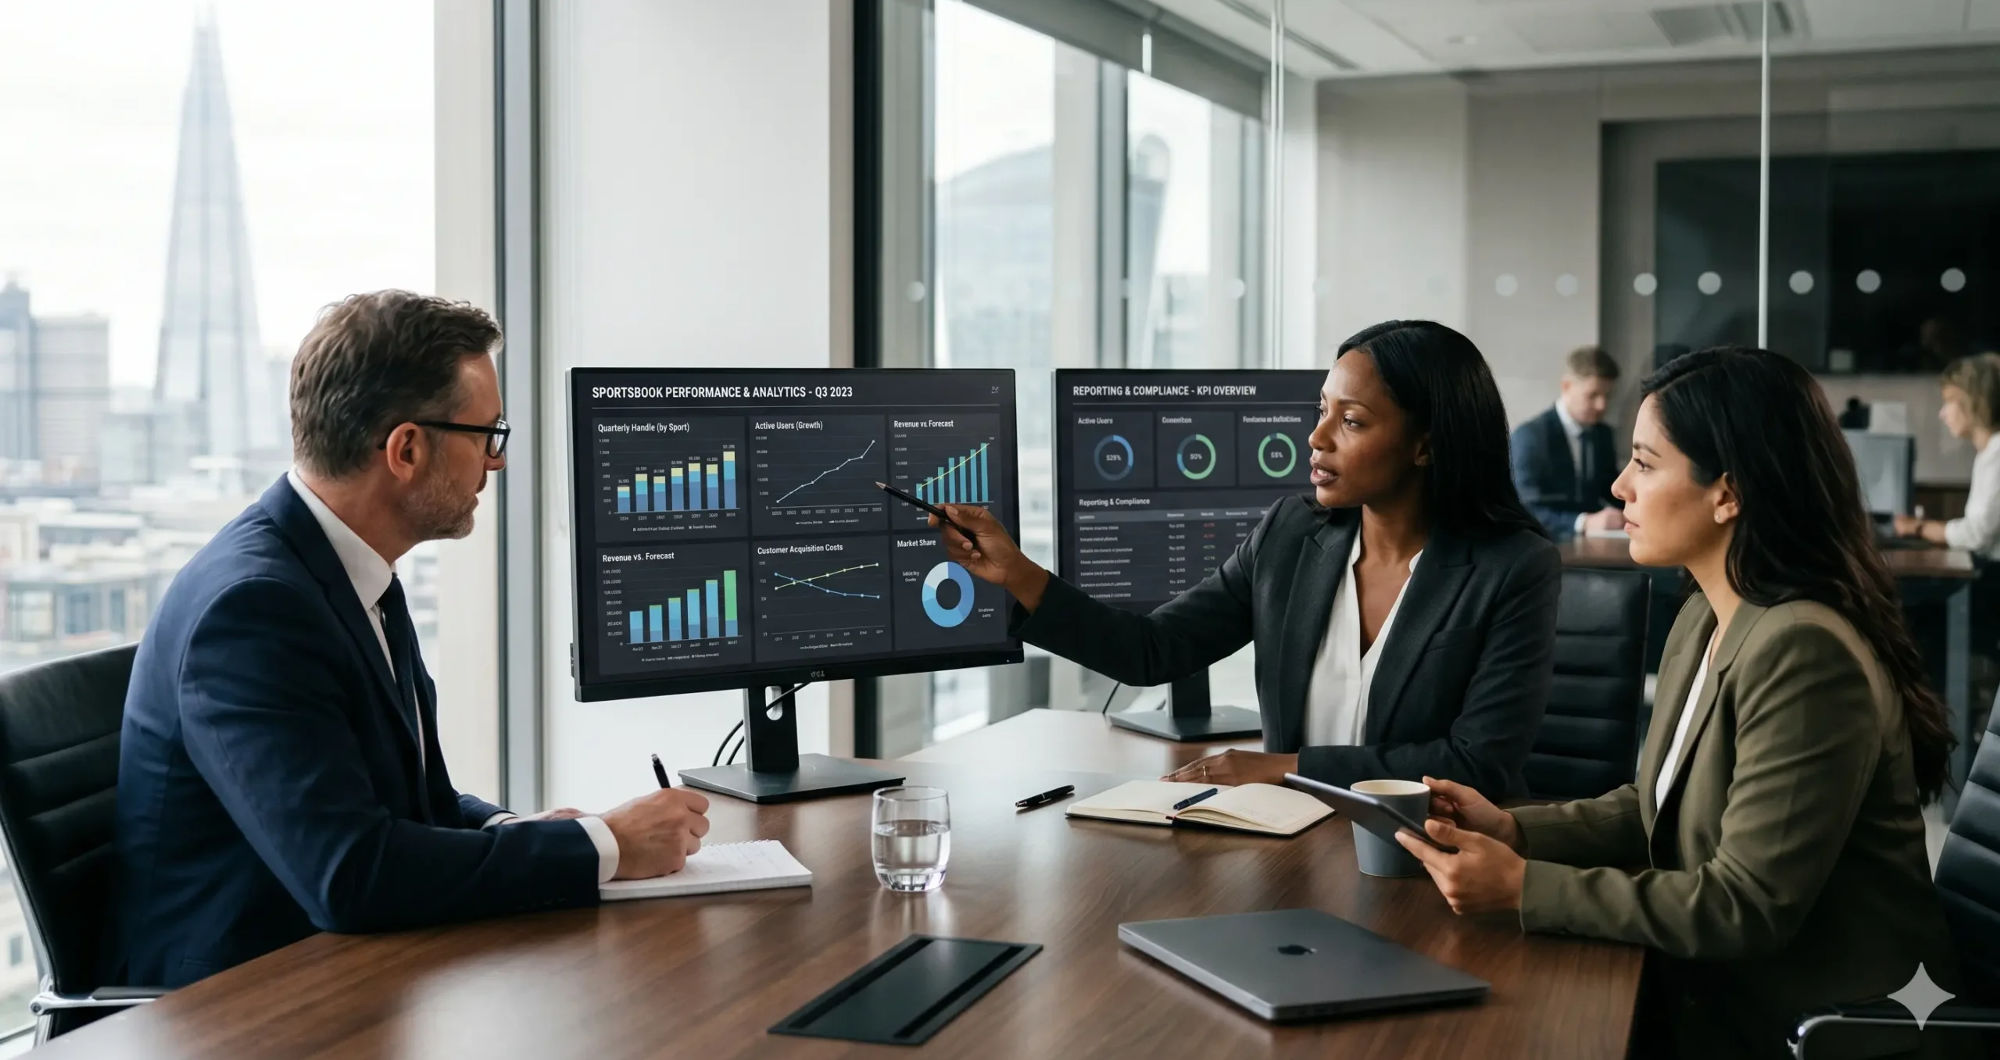
This is another common weak spot. The back office may look complete during a demo, but once the business is live, operators often realise that the reporting is only as flexible as the provider designed it to be. Finance wants a deeper view. Compliance needs an export with additional context. Operations wants more precise visibility into specific behaviours. The provider offers a workaround instead of direct control.
That kind of limitation can quietly affect decision quality for months before the business treats it as a platform issue.
Product and roadmap dependency
Roadmap dependency is rarely felt at launch. Operators feel it later, when they want to change something that matters commercially and find out the timeline is no longer theirs to control. Standard requests are fine. Non-standard ones become queue items.
For operators who need to differentiate or adapt quickly, that becomes a persistent source of friction.
Integration freedom
Third-party tools do not stand still. Payment providers change. CRM needs to evolve. Risk tools improve. KYC and fraud workflows shift. On a custom setup, teams can often make those decisions internally. On a white-label setup, those decisions usually depend on what the provider supports, approves, or prioritises.
That constraint may feel invisible at first. It does not stay invisible for long.
The Commercial Risks Buyers Underestimate
The real cost of a weak white-label decision often does not appear at launch. It appears later, once the operator is already dependent on the relationship.
Revenue share is one example. It can look commercially reasonable early on, especially when the priority is reducing initial burden. Once volume grows, however, the same structure can start dragging margin in ways that are far harder to unwind than they were to accept.
Data ownership is another area where assumptions often go unchallenged. Buyers may assume that access to data means portability. It does not always. A platform can provide visibility without making migration easy. That difference matters when the business wants to leave, expand differently, or reduce dependency.
Exit creates another problem. Migration rarely becomes easier once the platform is embedded in operations. Reporting formats, player data structures, payment dependencies, contractual terms, and workflow assumptions all make transition harder than the original sales process suggested.
That is why operators should not only ask what the platform costs to launch. They should also ask what the relationship costs to live with, adapt to, and eventually change.
What Operators Should Ask Before Signing
Before committing to a white-label provider, operators should push for direct answers to the questions that shape long-term control.
- What remains under the provider’s control after launch?
- Which reporting and compliance functions are directly accessible to the operator?
- What changes depend on the provider roadmap?
- How portable is the platform data if the operator wants to migrate later?
- What happens when a payments issue crosses platform and PSP boundaries?
- How do serious incidents escalate during major sporting events?
- What does the commercial model look like once volume grows?
- What will be harder to change six months after launch than it looks today?
Weak answers tend to sound familiar.
“That can usually be handled later.”
“Most things are configurable, but deeper changes would go through our team.”
“Migration is possible, but it depends on the future scope.”
The pattern is not always dishonesty. More often, it is deferral. But deferred clarity is still a risk when the operator needs that clarity at the point of decision.
Final Word
The right white label sportsbook provider is not simply the one that gets an operator live quickly. It is the one that gives the operator enough visibility, flexibility, and control to operate confidently once the platform is live and real pressure begins.
In the UK market, that matters even more. The easier question is how fast a platform can launch. The better question is whether the relationship still works when growth, regulation, and day to day operating demands begin testing it properly.